What Is Crypto Macro and Why Institutional Investors Are Paying Attention
Crypto macro is the discipline of reading digital asset markets through the same macroeconomic lens applied to equities, credit, and foreign exchange. Bitcoin's three largest trend reversals since 2020 each traced directly to Federal Reserve policy shifts, not on-chain technicals. Stablecoin.nyc tracks how these forces shape institutional allocation decisions, stablecoin flows, and on-chain capital deployment across cycles.
Definition: What Crypto Macro Actually Means
Crypto macro treats Bitcoin, Ethereum, and the broader on-chain economy as high-beta risk assets whose multi-month trend level is set by monetary policy, global liquidity, currency strength, and institutional risk appetite. It borrows the analytical toolkit built for rates, FX, and equities and applies it to a market that was, until recently, analyzed almost exclusively through order-book technicals and network activity charts. The framework maps directly onto the institutional crypto adoption wave now shaping treasury and allocator behavior.
The core framework
At its center, crypto macro asks a simple question: is the global liquidity environment expanding or contracting, and how is that flow being priced into non-yielding assets? Bitcoin's return profile responds to real yields, dollar strength, and credit spreads in ways that are now quantifiable across cycles. Ethereum inherits the same beta while adding its own yield and issuance dynamics. Recent crypto macro analysis has focused on how these variables interact with on-chain stablecoin supply and ETF absorption.
How it differs from technical analysis
Technical analysis identifies signals within existing trends. Macro analysis determines when trends begin and end. A trader using only chart patterns in 2022 saw repeated bullish setups play out against a structurally bearish backdrop and lost money on each one; the pattern was correct, the regime was not. The distinction between execution timing and regime identification is the central methodological upgrade macro provides, and it is the reason fundamentals-oriented research has migrated from a niche interest to a required input for allocators.
Takeaway: Charts tell you where you are inside a trend. Macro tells you whether the trend is real.
The Four Primary Macro Drivers for Bitcoin
Four variables account for most of Bitcoin's multi-month directional variance. None of them originate on-chain, which is precisely why they were underweighted by the first generation of crypto traders and are now overweighted by the second. A working analysis stack treats these as first-class inputs before it looks at anything else.
Fed policy cycles and liquidity
Federal Reserve easing, lower rates and quantitative easing, expands global liquidity and reduces the opportunity cost of holding non-yield-bearing assets. That is a structurally bullish backdrop for Bitcoin. Tightening does the reverse: higher rates raise the hurdle rate on every asset in the portfolio and drain the marginal dollar out of the risk complex. The 2022 hiking cycle, the fastest in forty years, produced the cleanest illustration of this mechanism on record, and it now anchors most institutional macro-driven crypto models.
Dollar strength and the DXY inverse relationship
The DXY and Bitcoin have shown a historically inverse relationship over medium-term cycles. A strengthening dollar typically reflects risk-off sentiment and higher US yields, both headwinds for BTC. A weakening dollar reflects the opposite: liquidity expansion, softer real yields, and capital rotation into risk. This relationship is not a physical constant, it can decouple for weeks at a time, but at the trend level it has held across the last three cycles and is now baked into how institutional desks position digital assets.
Risk-on / risk-off regime signals
Bitcoin trades as a high-beta risk asset. In risk-on regimes, low VIX, tightening credit spreads, and equity strength, it tends to outperform. In risk-off regimes, VIX spikes and credit stress, it sells off alongside equities but with amplified volatility. That amplification is the tell: Bitcoin is not a hedge in stress, it is the highest-beta expression of the risk book. Read alongside analytical coverage on regime shifts, this framing has replaced the "digital gold in a crisis" narrative among most professional allocators.
Institutional ETF flows as a demand indicator
Spot Bitcoin ETF weekly inflow and outflow data provides direct visibility into institutional demand that did not exist in prior cycles. Sustained inflows confirm incremental exposure; outflows during stress confirm de-risking. According to CryptoSlate reporting in September 2026, Bitcoin slipped below $85,000 as 10-year real yields hit 5.11%, a case where the flow channel and the yield channel moved in the same direction and compounded. The institutional flow picture is now consulted alongside price on almost every allocator dashboard.
Takeaway: Fed trajectory, DXY, risk regime, and ETF flows are the four inputs that set the trend. Everything else is execution.
Why the 2020–2024 Cycle Is the Clearest Case Study
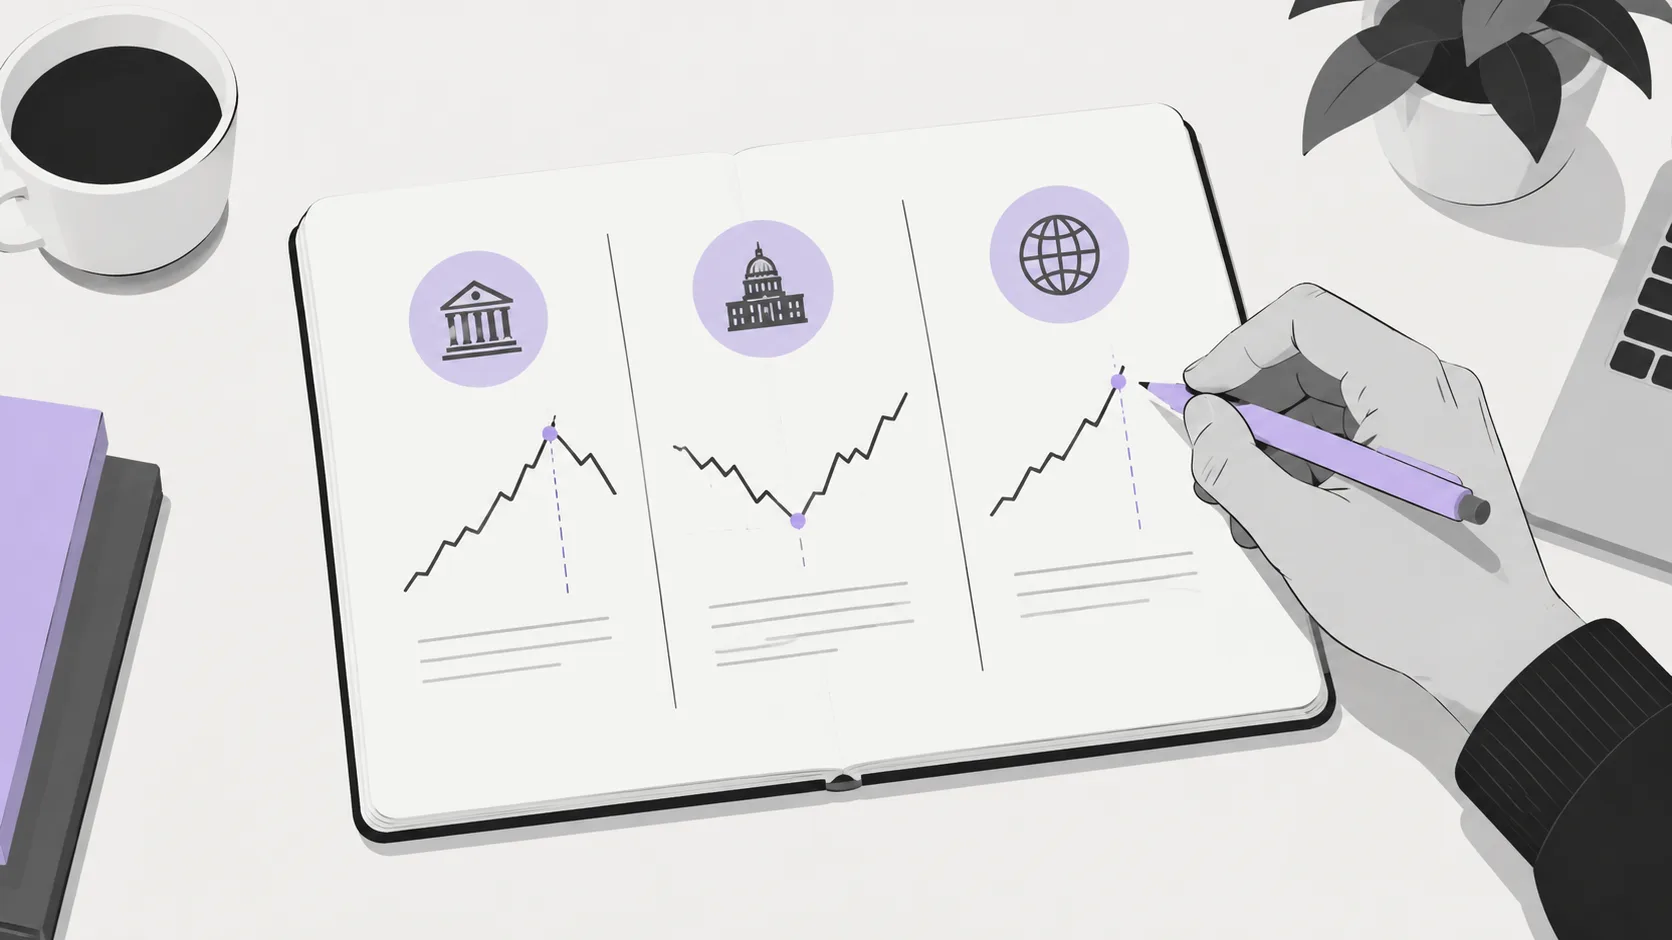
The last full cycle is the cleanest natural experiment crypto macro has produced. Three phases, three distinct policy regimes, and price action that lined up with each shift in a way that was hard to dismiss even for skeptics of the framework. It is worth walking through as one continuous fundamentals sequence rather than three separate trades.
The Fed accommodation bull run (2020–2021)
The 2020–2021 bull run coincided with peak Federal Reserve accommodation: near-zero rates, open-ended quantitative easing, and a weakening dollar. Every macro condition that a crypto macro model would flag as bullish was present simultaneously, and Bitcoin printed all-time highs against that backdrop. The narrative at the time credited retail flows and corporate treasury adoption; the mechanism underneath was liquidity. That period also seeded the first serious wave of corporate treasury interest in stablecoins as an on-chain analog to money-market exposure.
The rate-hike bear market (2022)
The 2022 bear market coincided with the fastest rate-hiking cycle in forty years. Bitcoin fell more than 75% from its peak, a drawdown consistent with macro tightening across the risk complex rather than an idiosyncratic crypto failure. FTX and the Luna collapse were real events with real consequences, but the direction of travel was already set by the Fed. Post-cycle institutional analysis largely converged on the view that the macro tape, not the credit events, wrote the bear market.
Rate-cut expectations and ETF recovery (2023–2024)
The 2023–2024 recovery aligned with rate-cut expectations and the launch of spot Bitcoin ETFs, which added an institutional demand channel that did not exist in prior cycles. Grayscale's September 2025 research reframed Bitcoin as an alternative monetary asset providing ballast against fiat currency debasement, a framing that gave allocators a portfolio-construction rationale beyond directional speculation. The recovery also validated the macro coverage lens: the same variables that called the top were consulted to call the turn.
Takeaway: One cycle, three regimes, three price responses. The mechanism is legible.
Why Institutional Investors Are Paying Attention Now
Institutional attention has migrated from "should we own any of this" to "how much, and when do we resize." The operational barriers, custody, execution, regulated wrappers, have compressed to a point where the remaining question is a portfolio-construction question, and portfolio-construction questions are macro questions. Coverage of institutional adoption trends tracks how allocators are formalizing this shift inside investment policy statements.
Bitcoin as a macro asset class
Allocators increasingly treat Bitcoin as a macro asset, allocated to based on risk appetite and portfolio construction rather than speculative conviction alone. Hard assets including Bitcoin and gold have gained momentum during periods of US fiscal stress, and Bitcoin has traded up materially against a backdrop of rising Treasury yields in specific windows where the fiscal-debasement thesis dominated the rate-drag thesis. The result is that Bitcoin now competes for a sleeve of the portfolio that used to belong exclusively to gold, real estate, and select tokenized real-world assets.
Stablecoins and on-chain capital as macro instruments
Stablecoins have become a macro-relevant instrument in their own right. Large on-chain stablecoin reserves function as dry powder whose deployment timing correlates with risk-on sentiment shifts, and total stablecoin float has become a leading indicator watched alongside money-market balances. The plumbing that moves this capital, including stablecoin payment rails and settlement layers, has matured to the point where treasury desks can hold, redeploy, and settle in the same instruments they analyze.
Corporate treasury adoption, sovereign wealth fund exploration, and regulated ETF structures have lowered the operational barriers that previously kept institutional capital sidelined. Allocators use crypto macro analysis to time exposure sizing, not just entry, deciding when to increase or reduce digital asset weight as part of a broader multi-asset strategy. The comparative literature on stablecoin settlement versus SWIFT is a useful adjacent read for treasurers building the operational side of that thesis.
Takeaway: Institutions are not asking whether crypto belongs in a portfolio. They are asking what the macro tape says about sizing it this quarter.
Common Misconceptions About Crypto Macro
Three misconceptions come up repeatedly in allocator conversations and retail commentary. Each one has a kernel of truth and a misleading conclusion, and each one is worth handling directly. The fundamentals archive treats these as recurring reader questions.
Misconception: Halvings drive macro trends
Reality: Halvings are supply events, not demand catalysts. They reduce new issuance on a schedule the market has known about for years, and their price impact is largely arbitraged into the forward curve. What determines whether reduced supply meets growing or contracting demand is the macro regime. The 2020 halving lined up with peak accommodation and produced a bull market; a halving that lands in a tightening cycle would not. This is one of the clearest examples in analytical coverage of a narrative that survives on pattern-matching rather than mechanism.
Misconception: Crypto is uncorrelated with traditional markets
Reality: Correlation is regime-dependent. It spikes during risk-off events, when everything is sold for liquidity, and compresses during risk-on periods when idiosyncratic drivers reassert themselves. The average correlation across a full cycle understates both extremes. A serious allocator models the conditional correlation, not the unconditional one, and the institutional research literature increasingly reflects that.
Misconception: Macro analysis is only relevant for Bitcoin
Reality: Macro conditions shape risk appetite across the entire on-chain ecosystem. DeFi protocol TVL, stablecoin issuance volumes, and NFT activity all compress during tightening cycles and expand during easing cycles. A trader using only technical analysis in 2022 saw bullish chart patterns play out against a structurally bearish macro backdrop and took systematic losses. The same lesson applies to on-chain traders reading TVL and yield charts in isolation, which is why broader stablecoin market coverage has become part of the macro read rather than a separate silo.
Takeaway: Halvings do not create liquidity, correlations are conditional, and macro sets the ceiling for on-chain activity of every kind.
How to Apply Crypto Macro to Allocation and Risk Management
A framework only earns its keep when it changes decisions. The practical use of crypto macro is upstream of trade execution: it sets the regime, and the regime sets the exposure band. Allocators building this discipline typically start with a small monitoring stack and expand it as resources on macro workflows become part of the desk routine.
Building a macro monitoring stack
A practical crypto macro monitoring stack tracks four things before it looks at price:
- Fed policy trajectory: CPI, FOMC communications, employment data, and the SOFR curve.
- DXY direction and the level of 10-year real yields.
- VIX and investment-grade / high-yield credit spreads.
- Spot Bitcoin ETF weekly flows and total stablecoin float.
Each of these is available in near real time from primary sources, and each one maps to a specific channel through which macro affects crypto. The stack sits on top of, not in place of, on-chain analytics; the two together form the input layer for allocation frameworks that a discretionary desk can actually execute against.
Translating macro signals into position sizing
Macro signals are most useful for trend-level context. Determine whether the structural backdrop favors or disfavors risk assets, then use on-chain and technical signals for execution timing within that regime. Stablecoin on-chain balances serve as a leading demand indicator: large idle reserves suggest capital waiting to deploy, while declining reserves during rallies confirm rotation into risk. This is where stablecoin market data starts to function as a macro instrument in its own right rather than a niche telemetry feed.
Institutional allocators typically translate this into exposure bands, underweight, neutral, overweight digital assets relative to a policy benchmark, that shift with the liquidity regime rather than with price momentum. The band moves first; the trade sizes into the band. That sequencing is the operational core of crypto macro, and it is what separates a macro-informed book from one that is simply reactive to the tape. Desks that want to see how this plays out at the treasury layer often start with the institutional adoption playbook before designing their own policy grid.
Takeaway: Macro sets the exposure band. On-chain and technical work sizes into it.
FAQ: Frequently Asked Questions
What does crypto macro mean?
Crypto macro is the analysis of digital assets through monetary policy cycles, global liquidity, currency strength, and institutional risk appetite. It applies the same framework used in equities, rates, and FX to Bitcoin, Ethereum, and on-chain capital markets.
How does Federal Reserve policy affect Bitcoin price?
Fed easing lowers the opportunity cost of holding non-yielding assets and expands global liquidity, a bullish backdrop for Bitcoin. Tightening does the reverse, raising hurdle rates and draining liquidity from the risk complex, which structurally pressures BTC.
Is Bitcoin correlated with the stock market?
Correlation is regime-dependent. During risk-off events Bitcoin correlates tightly with equities as both are sold for liquidity. During risk-on periods correlation compresses and idiosyncratic drivers dominate, so the average across a full cycle understates both extremes.
What is the DXY and why does it matter for crypto?
The DXY measures the US dollar against a basket of major currencies. It has shown a historically inverse relationship with Bitcoin over medium-term cycles: a stronger dollar reflects risk-off sentiment and higher yields, both headwinds for BTC.
How do institutional investors use macro analysis for crypto allocation?
Allocators use macro frameworks to set exposure bands, underweight, neutral, or overweight digital assets relative to a policy benchmark. Bands shift with the liquidity regime rather than price momentum, and individual trades size into the prevailing band.
What is a risk-on vs risk-off regime in crypto markets?
Risk-on regimes feature low VIX, tightening credit spreads, and equity strength, and Bitcoin typically outperforms. Risk-off regimes bring VIX spikes and credit stress, and Bitcoin sells off alongside equities but with amplified volatility due to its higher beta.
How do Bitcoin ETF flows fit into macro analysis?
Spot Bitcoin ETF weekly flows give direct visibility into institutional demand. Sustained inflows confirm incremental exposure and often align with easing regimes; outflows during stress confirm de-risking and typically coincide with tightening or risk-off conditions.
Does crypto macro analysis apply to altcoins and DeFi or just Bitcoin?
It applies across on-chain capital. DeFi TVL, stablecoin issuance, and NFT activity all compress during tightening cycles and expand during easing cycles. Macro sets the ceiling for risk appetite across the ecosystem, not just Bitcoin's price.
Conclusion
Crypto macro is not a new asset class, it is the correct framework for an asset class that was analyzed with the wrong tools for its first decade. Bitcoin's trend is set by liquidity, the dollar, risk regime, and institutional flows; on-chain and technical signals matter for execution inside that regime, not for calling it. The institutional migration underway is a direct consequence of that framework becoming legible enough to write into an investment policy statement. Ongoing coverage at Stablecoin.nyc tracks how allocators, treasurers, and builders are pricing that shift into their books. The open question is not whether macro drives crypto, that is settled; it is which macro variable dominates in the next regime.