What Is Real Estate Asset Tokenization? Explained
Real estate asset tokenization converts property rights into programmable digital tokens on a blockchain, making one of the world's largest and most illiquid asset classes tradable in fractions. The mechanics are straightforward; the implications for capital formation, settlement, and investor access are significant.
Definition: What Real Estate Tokenization Actually Means
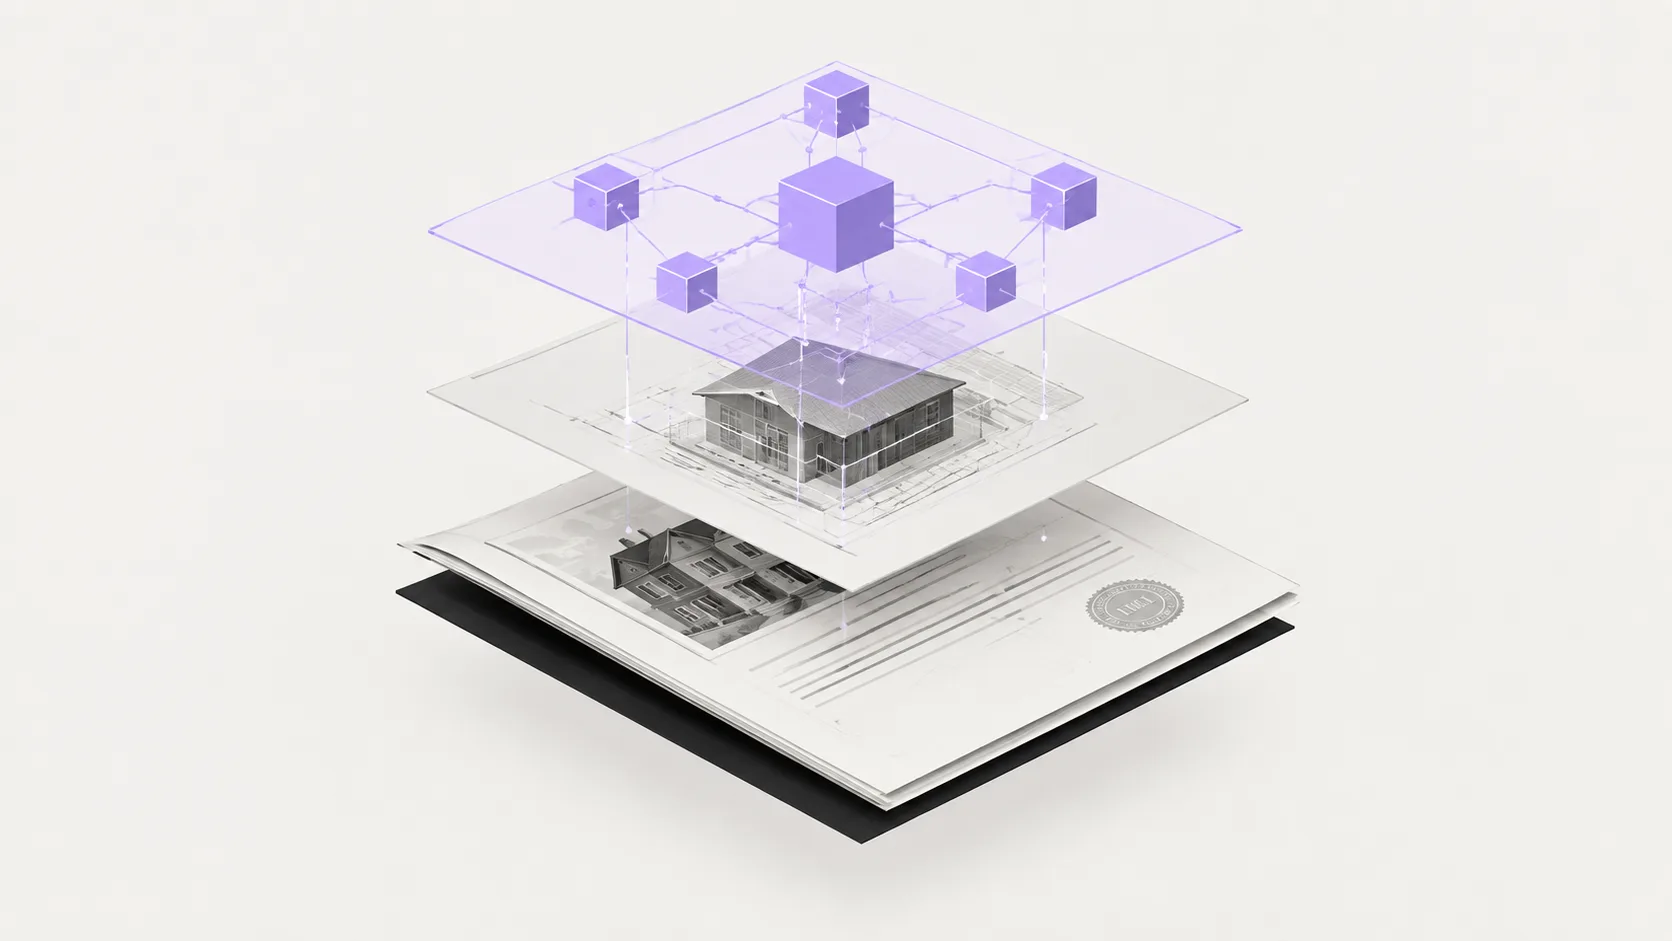
Real estate tokenization is the process of converting financial rights linked to a property, such as equity, debt, or income streams, into digital tokens issued on a blockchain. The token is a digital claim on rights, not a substitute for the property title itself. Everything above the token layer is standard property law; everything below it is programmable. That distinction shapes the entire design space, as explored in adjacent work on real-world asset issuance mechanics.
What a real estate token represents
A token typically represents a legally enforceable interest issued through a legal wrapper, most often a Special Purpose Vehicle (SPV) or trust structure that holds the property and defines investor rights contractually. Three common models dominate: fractional ownership tokens that convey equity in the SPV, cash flow tokens that convey rights to rental income or distributions, and debt participation tokens that convey a lender's position. Classification follows economic function, which is why this segment tracks so closely with the broader institutional tokenization thesis coverage.
What it does not represent
The token does not represent direct ownership of the physical building. The title deed remains held by the wrapper entity and remains governed by existing property, tax, and securities law in the asset's jurisdiction. The blockchain functions as an execution and record-keeping layer that automates cap table updates, distributions, and eligibility checks. It does not replace the courts, the recorder of deeds, or the securities regulator. A useful analog is the way custody structures shape settled markets, a theme picked up in the SEC custody rules review.
Takeaway: the token is a wrapper on a wrapper. It inherits the enforceability of the SPV and the property law behind it, and adds a programmable transfer and settlement layer on top.
How the Tokenization Process Works
The end-to-end workflow splits cleanly into three phases: structuring, issuance, and ongoing operations. Each phase has an off-chain leg and an on-chain leg, and the discipline lies in keeping the two synchronized. For a broader map of primary market mechanics across asset classes, the RWA primary market analysis is a useful reference.
Step 1: Legal structuring and asset preparation
Before any token is issued, the asset and its associated rights are identified and a legal structure is established to hold the property and define investor rights. An SPV is spun up, contracts are drafted with counsel, and the offering is scoped to a specific jurisdiction and exemption. This is where token classification is effectively decided, since the economic characteristics of the underlying instrument, equity or debt, drive the regulatory treatment far more than the choice of chain. Institutional desks approach this stage the way they would any private placement, a pattern visible in coverage of Goldman Sachs' tokenization desk expansion.
Step 2: Token issuance and investor onboarding
Tokens are issued on a blockchain via smart contracts once the legal structure is in place. Investor onboarding runs through KYC and AML verification in line with applicable securities regulations, and only verified wallets can receive allocations. Cap table entries update as tokens are minted and distributed. The onboarding pipeline is functionally similar to a broker-dealer subscription flow, with the compliance checks encoded into the transfer logic rather than sitting in a spreadsheet, a point discussed in fundamentals-level tokenization explainers.
Step 3: Ongoing management, distributions, and transfers
Smart contracts automate post-issuance workflows including dividend distributions, governance votes, and compliance-gated transfers. Transfers are typically restricted to verified investors and may carry lock-up periods or jurisdictional limitations baked directly into the token's transfer function. That constraint is a feature, not a bug: it is what allows the instrument to remain a compliant security while trading on a programmable rail. This is where operational efficiency shows up, in the same way stablecoin settlement compresses treasury workflows discussed in treasury-backed yield analysis.
Takeaway: the token is the settlement instrument. The compliance logic, the cap table, and the distribution schedule are all colocated with it, which is what collapses back-office costs.
Why Institutions Are Paying Attention: The Core Value Proposition
The interest is not aesthetic. It is a direct read on where friction and cost live in the current real estate stack, and where a programmable ledger can strip them out. The institutional argument reduces to three vectors: liquidity, cost, and programmability. Each has a measurable analog in current market structure, and each is being actively priced into desk build-outs tracked in institutional coverage.
Liquidity and fractional access
Fractional tokenization lowers minimum ticket sizes, which lets allocators build granular portfolios by geography, income profile, or risk tier instead of buying whole assets. A pension allocator that historically had to underwrite an entire multifamily complex can now assemble a slice across ten of them. That is a real change in portfolio construction, not a marketing line, and it maps to the same fractionalization logic driving demand across other on-chain instruments discussed in analysis coverage.
Cost reduction and settlement efficiency
Traditional intermediary costs in a home sale, including agents, lenders, title companies, and escrow, can account for 5 to 6 percent of a property's value, according to a Consumer Federation of America study cited by AWS. Blockchain transactions settle near-instantly and reduce reliance on manual processes, compressing the long closing timelines typical in commercial real estate. Programmable tokens can also automate recurring revenue mechanics such as settlement fees on secondary transfers, which is a genuinely new revenue model for issuers rather than a repackaging of an existing one, and adjacent to the broader compression in yields chronicled in liquidity trap coverage.
Portfolio customization and programmability
Programmability is the piece that gets underweighted. Once compliance, distributions, and transfer restrictions live in code, an issuer can slice a single asset into multiple economic profiles: a senior tranche with waterfall priority, a mezzanine strip, an equity kicker. Citibank projected the total addressable market for tokenized real estate at $1.5 trillion by 2030, and Deloitte research points toward roughly $4 trillion of tokenized commercial real estate by 2035. Those numbers are directional, but the direction is consistent, and it lines up with the collateral pivot discussed in sovereign debt and digital collateral.
Takeaway: the value is in unbundling the ownership stack. Liquidity, ticket size, and revenue mechanics each become independent design variables.
Common Misconceptions About Real Estate Tokenization
The category attracts a lot of loose thinking, most of it downstream of confusing the token with the asset. A few points worth being precise on, in the same spirit as the framing used in fundamentals coverage.
Misconception: The token is the deed. Reality: Legal title stays off-chain.
Tokenization cannot directly modify the legal concept of property ownership. The title deed remains governed by property law and held by the legal wrapper entity. A blockchain record of a transfer does not, by itself, convey ownership; enforceability flows through the SPV and the underlying contract, a nuance frequently raised in macro-level analysis of on-chain instruments.
Misconception: Tokenization means instant liquidity. Reality: Liquidity is constrained by compliance rails.
Secondary market liquidity for tokenized real estate is real but conditional. Transfers are restricted to verified counterparties on approved platforms, not open-market crypto trading. The liquidity curve is shaped more by the compliance whitelist and platform depth than by chain-level throughput, which is why comparisons to spot crypto markets miss the point. The dynamics are closer to those in regulated secondary markets, a theme touched on in spot ETF volume coverage.
Misconception: Any property can be tokenized easily. Reality: Jurisdiction and structure matter enormously.
Cross-border tokenization requires configurable compliance rules per jurisdiction. A token issued in one legal regime may not be transferable to investors in another without separate structuring. NFTs used in some pilot cases to represent property documentation do not confer ownership unless backed by enforceable off-chain contracts. Token classification as a security in most jurisdictions means these instruments carry the same disclosure and registration burden as traditional offerings, a point that maps onto ongoing legislative debate covered in the Stablecoin Act update.
Takeaway: the technology is the easy part. The legal wrapper, the exemption chosen, and the counterparty whitelist do the actual work.
Regulatory and Compliance Considerations
Regulation is not an afterthought here; it is the design constraint that determines whether a token can be issued, held, and transferred at all. The good news is that most of the required primitives already exist, and issuers are learning to encode them directly. The bad news is that they vary sharply by jurisdiction, a theme covered in MiCA 2.0 analysis.
Securities law and token classification
The legal treatment follows the rights attached to the token and the jurisdiction of the offering. Tokenized equity or debt can fall within securities law; a blockchain record does not create an exemption. In the EU, MiCA Article 2 excludes crypto-assets that qualify as financial instruments. Such instruments remain subject to the applicable financial-services framework. Transfer controls in a smart contract can support compliance, but they do not establish that an offering meets every legal requirement.
Jurisdiction-specific structuring
A structure permitted in one jurisdiction may require a different offering route, investor restrictions, or legal entity in another. Issuers need to assess property rights, securities classification, tax, custody and data handling together. Privacy technology can restrict access to on-chain information; it does not, by itself, satisfy a regulator or make investor rights enforceable.
Takeaway: compliance is not a wrapper you bolt on. It is a first-class design input that decides which investors can hold the token, on which platforms, and under what conditions.
Conclusion
Real estate tokenization is a structural change to how property rights are issued, transferred, and held, not a speculative overlay on the existing market. The thesis is narrow and defensible: programmable legal rights, lower settlement costs, and fractional access address genuine inefficiencies in a multi-trillion dollar asset class. Where the market goes from here depends less on chain performance and more on how quickly legal, regulatory, and custody infrastructure catches up..
The bottleneck is not the technology. It is the legal wrappering, compliance automation, and custody arrangements required to make tokens enforceable and transferable at institutional scale. Early institutional movers are gaining familiarity with SPV structuring, compliance-gated secondary markets, and on-chain cap table management before these patterns become standard, which is the same first-mover pattern that showed up in the previous cycle's infrastructure build described in the de-pegging paradox. The open question is whether tokenization becomes the default rail for private real estate offerings within this cycle or the next.
Frequently Asked Questions
What is the difference between a tokenized real estate asset and a REIT?
A REIT is a pooled, publicly traded fund that owns a portfolio of properties and distributes taxable income under a specific corporate regime. A tokenized real estate asset is typically a direct SPV interest in a single deal, held on-chain with programmable transfer restrictions.
Do real estate tokens give investors legal ownership of a property?
No. Tokens represent legally enforceable rights in a wrapper entity, usually an SPV or trust, that holds the property. The token conveys equity, debt, or income rights in that entity; the deed itself remains with the wrapper and is governed by property law.
What blockchain networks are used for real estate tokenization?
Issuers use permissioned and public chains including Ethereum, Polygon, Avalanche, Provenance, and Polymesh. Choice depends on compliance features such as identity gating and confidential assets, transaction costs, and integration with existing custody and transfer agent infrastructure required by the deal.
How is liquidity created for tokenized real estate?
Liquidity comes from compliance-permitted secondary venues where verified investors can buy and sell tokens under the same transfer rules encoded at issuance. Deeper liquidity requires broader investor whitelists, platform interoperability, and standardized disclosures, not simply listing the token on an open exchange.
What regulations apply to tokenized real estate in the United States?
The rights represented by the token determine the securities-law analysis. An offer or sale of securities must be registered or use an available exemption. The SEC describes routes including Regulation D, Regulation A and Regulation Crowdfunding, each with distinct conditions. Tokenization does not remove those conditions.
What is a Special Purpose Vehicle (SPV) in the context of real estate tokenization?
An SPV is a company established specifically to hold a property and issue tokenized interests against it. Investors acquire economic or governance rights in the SPV via tokens, isolating the asset from the sponsor's balance sheet and creating a clean legal container for the offering.
How large is the tokenized real estate market expected to become?
Forecasts vary. Citibank projected roughly $1.5 trillion in tokenized real estate by 2030, while Deloitte research points toward around $4 trillion of tokenized commercial real estate by 2035. Numbers are directional but the trajectory across major analyst forecasts is consistent.
Can retail investors participate in tokenized real estate offerings?
Retail participation depends on the offering route and the investor eligibility rules for that specific instrument. Registration and certain exemptions can permit non-accredited investors; other offerings restrict participation. The practical question is which rights an investor can enforce and through which compliant transfer market, rather than whether the asset has a token.