What Is On and Off-Ramp in Digital Assets Explained
On-ramps and off-ramps are the transaction infrastructure that connects fiat currency to the crypto ecosystem and back again. Without them, digital assets remain isolated from the broader economy. Understanding how these rails work, where they break down, and why off-ramps are structurally harder to build than on-ramps is foundational for any treasurer, builder, or allocator operating at the intersection of traditional finance and on-chain systems.
Definition: What On-Ramps and Off-Ramps Actually Are
On and off-ramps are not products. They are processes. Each spans payment acceptance, identity verification, conversion execution, and settlement across two regulatory regimes that were never designed to interoperate. The ramp sits at the seam between regulated banking infrastructure and permissionless blockchain networks, which makes it the primary compliance and risk surface for anyone moving value between the two systems.
On-Ramp: The Fiat-to-Crypto Entry Path
An on-ramp converts fiat currency, typically USD, EUR, or GBP, into cryptocurrency or digital assets. It is the entry point into the crypto ecosystem for a new user, a trading firm funding an account, or a corporate treasury acquiring stablecoin exposure. The on-ramp provider accepts a bank transfer, card payment, or alternative local payment method, runs required compliance checks, executes the conversion at a market price, and assigns the resulting crypto to a specified wallet address.
Off-Ramp: The Crypto-to-Fiat Exit Path
An off-ramp performs the reverse: it accepts cryptocurrency from a user or business, converts the proceeds back to fiat, and settles to a bank account or card. The mechanics look symmetrical on paper. In practice, off-ramps are the harder engineering problem because they require live banking relationships in every destination jurisdiction and must manage fraud risk on an asset that cannot be reversed once it has moved on-chain.
Section takeaway: Treat ramps as a four-step process (deposit, verify, convert, settle), not a single product. The compliance and risk work lives in the verify and settle steps, not the conversion itself.
How On-Ramps and Off-Ramps Work: The Mechanics
The underlying flows are well documented across providers, but the operational details determine whether a ramp is usable at institutional scale or only for retail-sized tickets.
The On-Ramp Flow: Deposit, Verify, Convert, Assign
A typical centralized on-ramp follows four steps:
- The user links a bank account or card and completes KYC.
- Fiat is deposited via bank transfer, SEPA, Faster Payments, ACH, or card rail.
- The provider runs AML, sanctions, and transaction monitoring checks.
- The provider executes the conversion at a quoted price and credits the destination wallet.
The published explanation from Finst's crypto academy describes this same loop, with price discovery, liquidity, and transaction cost as the operational variables that determine quality of execution.
The Off-Ramp Flow: Sell, Convert, Settle to Bank
Off-ramps mirror the on-ramp sequence in reverse. The user sends crypto to a provider-controlled address, the provider sells it against a fiat pair at spot, and the proceeds are routed to the user's nominated bank account. The settle step is where off-ramps diverge sharply from on-ramps: a bank transfer out requires an active correspondent relationship in the destination currency, which few providers hold at breadth.
Centralized vs. Decentralized Ramps
Centralized venues, including regulated exchanges, brokers, and payment processors, dominate fiat-to-crypto flow because decentralized protocols cannot directly interface with fiat banking rails. Decentralized exchanges handle crypto-to-crypto swaps efficiently, but fiat ingress and egress still flow almost exclusively through centralized intermediaries operating under frameworks such as MiCAR in Europe or state-level money transmitter licensing in the United States.
Total cost of a ramp conversion includes four layers:
| Cost layer | Who captures it | Typical impact |
|---|---|---|
| FX spread | Market maker or liquidity provider | Often largest, usually hidden |
| Network fee | Blockchain validators | Variable, driven by congestion |
| Processor margin | Ramp provider | Headline rate quoted here |
| Compliance overhead | Ramp provider | Embedded in processor margin |
Section takeaway: The quoted fee rarely equals total cost. The spread is where providers compete on economics, and it is where sophisticated buyers negotiate.
Why Off-Ramps Are the Harder Problem
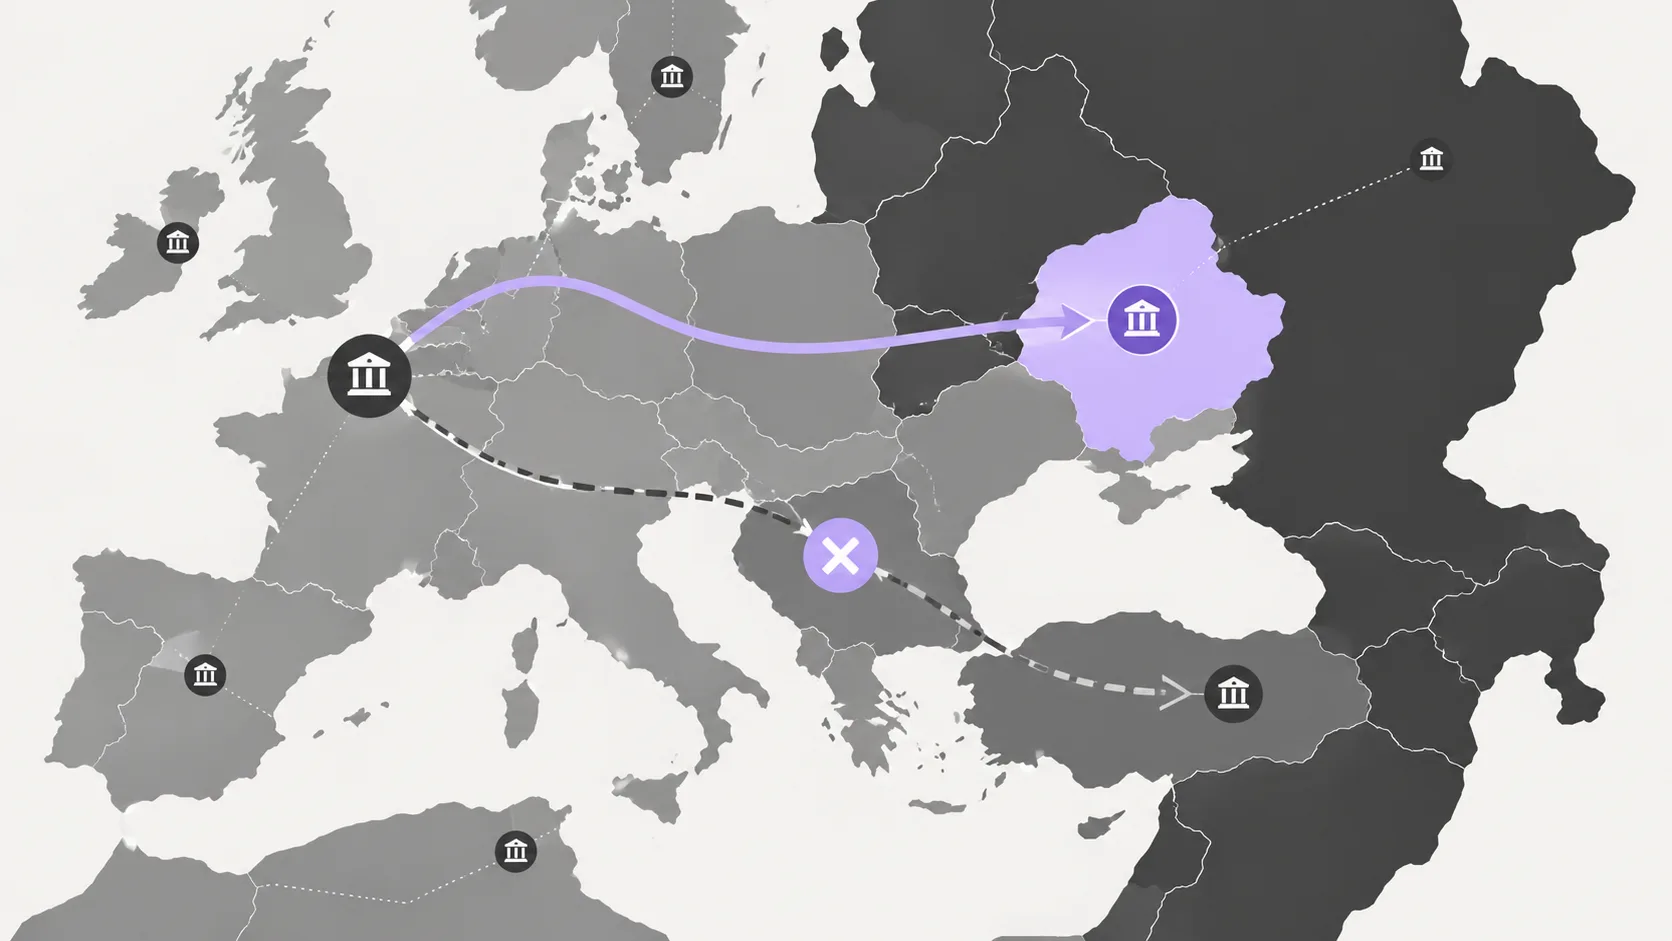
On-ramps are relatively mature. Off-ramps remain the structural bottleneck for Web3 products, and the gap is widening as the number of destination jurisdictions a serious platform needs to support grows. This asymmetry is covered well in LinkedIn analysis of Web3 ramp infrastructure, which frames off-ramps as the point where most Web3 user journeys quietly fail.
Regulatory Fragmentation by Jurisdiction
Compliance requirements for off-ramps vary by country and by asset type. A provider licensed under MiCAR to serve EU residents may hold no banking relationship in Southeast Asia, no e-money license in Latin America, and no money transmitter coverage in the US states that matter. Each new destination corridor requires a new license, a new banking partner, and a new local AML program. The result is a patchwork, not a network.
Banking Rail Integration Complexity
Correspondent banking is the choke point. Off-ramps need settlement accounts at banks willing to process crypto-related flows, and the universe of such banks is narrow and shifting. For teams building toward broader coverage of this surface, the breakdown in digital asset payments infrastructure is a useful next read on where the rails actually integrate today.
The UX Trust Gap at Payout
For platforms, a failed off-ramp is the highest-friction moment in the entire user lifecycle. A user who cannot withdraw to local currency does not conclude that the destination bank is slow; they conclude that funds are trapped on-chain. Retention collapses at that exact point. Off-ramps also carry higher fraud and chargeback risk than on-ramps, because an irreversible crypto payout can be paired with a reversible upstream fiat deposit, creating a classic asymmetric settlement attack.
Stablecoin off-ramps, typically USDC or USDT settling to a USD or EUR bank transfer, are increasingly the preferred path. They remove the FX volatility between order and settlement, simplify the conversion step to near-par, and align with the direction of institutional stablecoin adoption generally.
Section takeaway: The hard part of an off-ramp is not the sell, it is the bank account on the receiving side in the right currency.
Who Uses On/Off-Ramps and For What
The user base for ramps is more diverse than retail on-ramp marketing suggests. The economics and the compliance posture change meaningfully depending on which cohort is being served.
Institutional and Corporate Use Cases
Institutions use ramps to fund trading accounts, settle OTC transactions, manage treasury exposure between fiat and digital assets, and pay out local currency after receiving crypto revenue. Exchanges rely on ramps as core infrastructure; without them, the exchange is crypto-only and inaccessible to any user starting from a bank account. Market structure precedents such as BlackRock's tokenized treasury liquidity fund illustrate how restrictions on competing sovereign digital currency frameworks sharpen demand for institutional-grade ramp capacity, because subscriptions and redemptions ultimately clear in fiat.
Consumer and Retail Use Cases
Retail users buy crypto for investment, pay for goods and services, and increasingly hold stablecoin balances in neobank-style apps. Fintechs embedding crypto need ramp APIs that integrate invisibly into the user experience rather than redirecting to a third-party exchange. Embedded flows consistently outperform redirect flows on conversion and retention.
Emerging Market and Remittance Applications
The clearest value proposition for ramps today is in cross-border payments. The pattern:
- Sender deposits local fiat with a provider in country A.
- Provider converts to a stablecoin on-chain.
- Stablecoin is transmitted to a provider in country B.
- Country B provider off-ramps to local fiat and pays the recipient.
The flow replaces a two-to-five-day SWIFT path with a settlement that resolves in minutes, at a fraction of the correspondent banking cost. Gaming platforms, NFT marketplaces, and DeFi protocols with real-world payouts rely on the same stack to convert on-chain earnings into usable fiat for their users.
Section takeaway: The use case determines the required ramp. Trading desks need deep spot liquidity and fast settlement; remittance platforms need breadth of destination currencies and reliable last-mile payout.
Compliance and Risk at the Ramp
Ramps are the primary point where regulated financial controls can be meaningfully applied to crypto activity. Once value moves deeper into permissionless infrastructure, traceability degrades quickly, and the opportunity to connect a transaction back to an accountable customer relationship shrinks.
KYC, AML, and Source-of-Funds Controls
KYC at onboarding establishes the customer relationship. Ongoing AML monitoring at the ramp flags unusual transfer patterns, volume spikes, and layering behavior. Source-of-funds review is particularly relevant at off-ramps, where institutions must connect proceeds back to a legitimate customer relationship before settling to fiat. Weak controls at this boundary are what regulators focus on, because this is where observable financial activity actually exists.
Sanctions Screening and Transaction Monitoring
Sanctions screening must occur at both ends. The on-ramp blocks prohibited jurisdictions or sanctioned wallets from entering the ecosystem. The off-ramp prevents proceeds from reaching sanctioned beneficiaries, which is a harder problem because the originating transaction may have been several hops upstream.
Audit Trail and Regulatory Obligations
MiCAR in the EU, FinCEN rules in the US, and equivalent national regimes impose travel rule and reporting obligations specifically at the ramp boundary. Related custody obligations tighten the picture further; the shift documented in the SEC's revisiting of custody rules for digital asset managers is directly relevant for any firm whose operational model combines ramping with holding client assets.
Section takeaway: Ramps are observable; downstream crypto activity often is not. Build the compliance program at the boundary where you can actually see the transaction.
Choosing a Ramp Provider: What Actually Matters
Procurement conversations tend to anchor on headline fee rates. That is the wrong anchor. The variables that determine whether a ramp works operationally are coverage, true cost, licensing posture, reliability, and integration depth.
Currency and Rail Coverage
Coverage comes first. A provider that supports 30+ fiat currencies across SEPA, Faster Payments, ACH, SWIFT, and relevant local rails is meaningfully more useful than one with narrow geographic reach. For a global business, each missing corridor is a user cohort that cannot be served.
Fee Structure and Spread Transparency
Fee transparency is operationally critical. Providers often quote a tight headline rate and embed margin in the FX spread. Total cost of conversion must account for both. Request mid-market reference pricing alongside the quoted rate; if the provider will not provide it, assume the spread is where the real margin lives.
Compliance Posture and Licensing
Licensing determines which jurisdictions a provider can legally serve. Operating through an unlicensed ramp creates compliance exposure for the downstream business, not just the ramp provider. Reliability and uptime are underappreciated: a ramp that fails during high-volatility periods forces businesses to hold unwanted crypto exposure until conversion resumes.
API quality determines whether ramp functionality is embedded natively or users must leave the product. Teams evaluating specific providers can start with the comparison in best crypto on-ramp platforms, which maps coverage and licensing posture across the main venues.
A quick evaluation checklist:
- Fiat currencies supported and the specific local rails behind them.
- Published spread methodology and mid-market reference.
- License register entries, by jurisdiction, verifiable with the regulator.
- Uptime SLA and historical incident disclosure.
- API documentation quality and sandbox availability.
- Chargeback and fraud policy, especially on off-ramp side.
Section takeaway: Rank providers on coverage and true cost, not on the number quoted in the sales deck.
FAQ: Frequently Asked Questions
What is the difference between a crypto on-ramp and an off-ramp?
An on-ramp converts fiat currency into cryptocurrency and credits a wallet. An off-ramp does the reverse, selling crypto and settling the proceeds in fiat to a bank account. Both sit at the fiat-crypto boundary and apply regulated compliance controls.
How long does it take to on-ramp or off-ramp crypto?
Card-based on-ramps typically settle in minutes. Bank transfers depend on the underlying rail: SEPA Instant and Faster Payments clear in seconds, ACH takes one to three business days, and SWIFT off-ramps can take two to five business days depending on correspondent routing.
Are on-ramps and off-ramps regulated?
Yes, in nearly every major jurisdiction. Providers operate under frameworks such as MiCAR in the EU, FinCEN registration in the US, and local money transmitter or e-money licensing elsewhere. KYC, AML, sanctions screening, and travel rule obligations apply at the ramp boundary.
What fees are involved in crypto on-ramps and off-ramps?
Four cost layers usually apply: the processor fee quoted upfront, the FX or conversion spread embedded in the price, blockchain network fees, and any receiving bank or card charges. The spread is often the largest and least visible of these components.
Can stablecoins be used as on-ramps or off-ramps?
Stablecoins function as the preferred asset for ramp flows because they minimize FX volatility between order and settlement. A USDC off-ramp to a USD bank account is near-par and avoids the spot volatility risk of settling against bitcoin or ether.
Why are off-ramps harder to build than on-ramps?
Off-ramps require live banking relationships in every destination currency, carry higher fraud and chargeback risk because crypto transactions cannot be reversed, and must satisfy more intensive source-of-funds review before settlement. On-ramps face none of these three constraints at the same severity.
What is the best way to off-ramp large amounts of crypto to fiat?
Large tickets are typically handled through regulated OTC desks or institutional prime brokers that quote a block price, settle via wire or SWIFT, and provide full compliance documentation. Retail exchange withdrawals are usually unsuitable above low-six-figure amounts due to liquidity, limits, and reporting friction.
Do decentralized exchanges support fiat on-ramps and off-ramps?
Not directly. Decentralized exchanges handle crypto-to-crypto swaps. Fiat ingress and egress still flow through centralized intermediaries, often integrated into DEX front ends via third-party ramp widgets. The fiat leg itself remains a centralized, regulated transaction.
Conclusion
Ramps are the connective tissue of the digital asset economy. On-ramps are largely a solved problem for the main currency corridors; off-ramps are not, and the gap will widen as more real-world activity settles on-chain and needs to settle back out again. The practical implication for operators is that ramp selection is a strategic decision, not a procurement footnote. Treat the fiat-crypto boundary as the point where coverage, compliance, and true cost actually determine whether a product works at scale. Builders and treasurers evaluating this surface can continue with the broader context in the coverage of digital asset payment platforms and use it to pressure-test provider shortlists against the criteria above.