Tokenized Money Market Funds: How On-Chain MMFs Actually Work
Tokenized money market funds (tMMFs) are one of the few on-chain instruments that deliver institutional-grade yield, capital preservation, and programmable settlement inside a single wrapper. They are not a new asset class. They are traditional MMF shares re-issued on a distributed ledger, which changes the rails without changing the underlying exposure. Understanding how that re-issuance works, and where it genuinely improves on legacy infrastructure, is now baseline competency for any treasurer or allocator operating across both traditional and digital markets.
Definition: What a Tokenized Money Market Fund Actually Is
A tMMF is a conventional money market fund whose shares are represented as digital tokens on a blockchain or distributed ledger. The portfolio composition does not change: short-duration government securities, repo, and cash remain the underlying exposure. The innovation is at the recordkeeping layer, not the asset layer.
The underlying asset is unchanged
A share in Franklin Templeton's FOBXX or BlackRock's BUIDL is still a claim on a conservatively managed, capital-preservation-focused portfolio. Investors receive the same yield profile, the same NAV mechanics, and the same credit exposure as a non-tokenized equivalent. What differs is how ownership is recorded, how shares move, and what else can be programmed around them. This matters for compliance and risk framing: tokenization is an operational modernization, not a repricing of the underlying.
What tokenization adds to the record
Ownership shifts from an account-based entry maintained by a transfer agent to a token-based entry on a shared ledger. In most live implementations the tokens are permissioned or whitelisted, meaning the smart contract itself enforces eligibility: only KYC-approved wallets can hold, transfer, or redeem shares. State Street's comparison framework describes this as moving from intermediated recordkeeping to a jointly maintained ledger with native auditability.
Three on-chain cash-like categories now coexist and should not be conflated:
- Stablecoins: non-yield-bearing or yield-passing tokens pegged to a reference asset.
- Deposit tokens: bank-issued tokens representing deposit liabilities.
- Tokenized MMFs: fund shares with regulated issuer structures and short-duration government exposure.
Each has a distinct issuer, a distinct risk profile, and a distinct regulatory treatment. The most-cited live tMMFs are Franklin Templeton's FOBXX, Circle/Hashnote's USYC, and BlackRock's BUIDL, with BUIDL reaching roughly $2.5B in AUM as of mid-2025 per the New York Fed's Liberty Street Economics analysis. For a product-level breakdown of the largest live fund, see our note on BlackRock's BUIDL fund.
Takeaway: A tMMF changes the ledger, not the portfolio. Treat it as infrastructure modernization applied to a known asset.
How the Mechanics Work: From Subscription to Token
The subscription lifecycle looks familiar to any treasurer who has onboarded a traditional fund, with a single additional step: wallet provisioning.
Onboarding and KYC
Investors complete standard AML and KYC checks and provide a blockchain wallet address that will be whitelisted at the smart-contract level. In practice this means the issuer or its transfer agent maintains an allowlist of addresses eligible to receive tokens. Any transfer to a non-whitelisted address is rejected by the contract itself rather than policed after the fact. The onboarding workflow mirrors traditional fund processes; the on-chain wallet step is additive, not substitutive. For a fuller view of how tokenized assets move from issuance to secondary circulation, see our overview of real-world asset primary market dynamics.
Minting, transfer, and redemption
Subscriptions can settle in fiat or in stablecoins, with the issuer minting tokens to the investor's whitelisted address once funds clear. Redemptions reverse the flow: tokens are burned and the investor receives fiat or stablecoin proceeds. Between those endpoints, transfers between whitelisted investors are direct ledger updates rather than subscription/redemption round-trips through a transfer agent. This is the mechanical reason tMMFs can support intraday mobility that legacy MMFs structurally cannot.
Settlement and atomic delivery-versus-payment
Smart contracts allow asset transfer and payment to execute in a single atomic transaction, a configuration known as delivery-versus-payment (DvP). Either both legs settle or neither does, which eliminates principal risk in the settlement window. According to J.P. Morgan Asset Management's tokenization research, this also lets issuers automate dividend distribution and interest accrual, reducing manual reconciliation and operational error rates. Blockchain-based transfers can settle in near real time, a structural improvement on the T+1 or T+2 cutoffs that still define legacy MMF rails.
Takeaway: The mechanical edge is atomic settlement plus programmable transfer logic. That edge is only realized when the counterparty is also on the same ledger.
The Three Use Cases That Actually Drive Adoption
The New York Fed identifies three use cases for tokenized investment funds that are either difficult or impossible for traditional MMFs: collateral mobility, on-chain treasury management, and yield-bearing reserves for crypto-native platforms. Each one maps to a specific operational pain point.
Collateral mobility
This is the use case with the largest institutional pull. Tokenized shares can be posted, moved, and reused across counterparties intraday without waiting for T+1 settlement. During margin calls or volatile markets, the ability to mobilize collateral in minutes rather than hours is materially valuable. The BIS documented tMMFs as a fast-growing collateral asset through 2025, and prime brokers and clearinghouses have begun piloting their acceptance as eligible margin.
On-chain treasury management
Corporate treasuries and crypto-native companies increasingly hold tMMFs as yield-bearing alternatives to idle stablecoins. A DAO treasury parked in USDC earns nothing; the same balance rotated into a whitelisted tMMF position earns short-duration Treasury yield while retaining near-instant redemption optionality. The practical bar is wallet-level KYC and issuer onboarding; the practical upside is converting a cost center into a modest yield line.
24/7 liquidity for crypto-native operators
Legacy MMF rails close at specific cutoffs and do not operate on weekends. Tokenized rails do not share those constraints. For a global institution operating across time zones, or a crypto exchange managing weekend settlement obligations, that difference matters. The tradeoff is that off-hours liquidity is only as deep as the whitelisted counterparty pool is wide, which remains a limiting factor today.
Takeaway: Adoption is driven by collateral mobility and 24/7 operability, not by yield. The underlying yield is the same yield. The novelty is what you can do with the share while you hold it.
tMMFs vs. Traditional MMFs: What Actually Changes
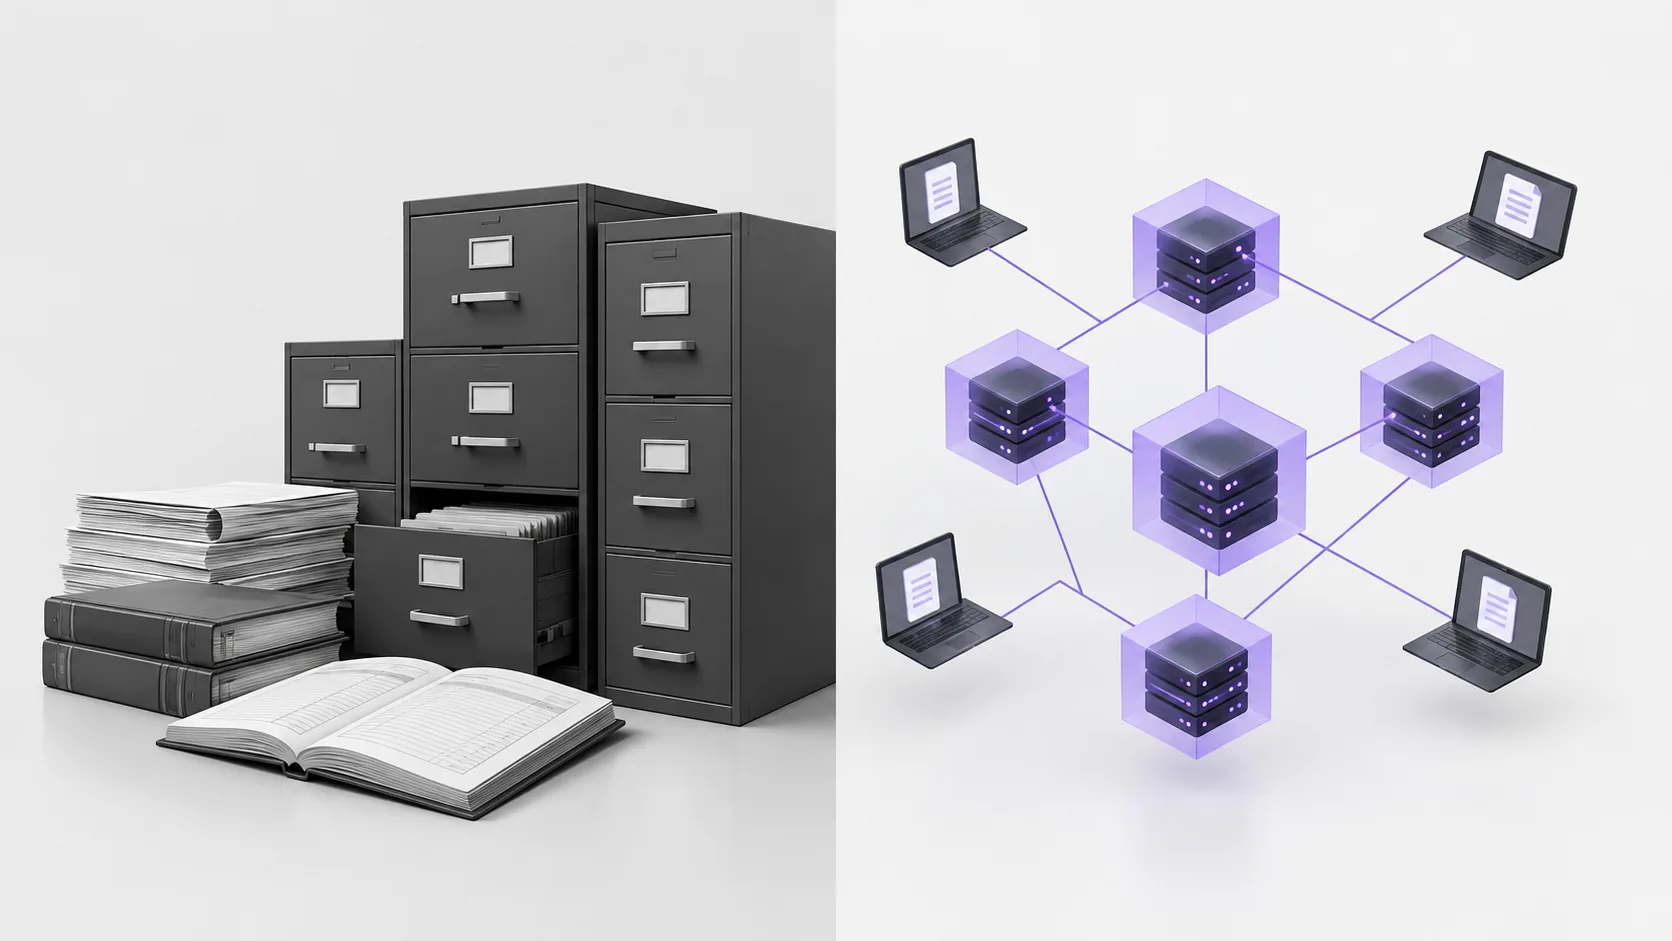
The comparison is cleaner when framed as a table of what moves and what does not.
| Feature | Traditional MMF | Tokenized MMF |
|---|---|---|
| Ownership record | Account-based, maintained by transfer agent | Token-based entry on a shared ledger |
| Transfer mechanism | Subscription/redemption via transfer agent | Direct wallet-to-wallet within whitelist |
| Settlement window | T+1 or T+2, time-based cutoffs | Near real-time, 24/7 |
| Collateral mobility | Operationally slow | Intraday within permitted venues |
| Transparency | Periodic reporting | Continuous ledger visibility |
| Compliance enforcement | Off-chain gatekeeping | Smart-contract whitelists plus off-chain KYC |
| Underlying portfolio | Short-duration govt securities, cash | Short-duration govt securities, cash |
| Risk profile | Low, capital-preservation | Low, capital-preservation |
Ownership records and transparency
Account-based records require periodic reconciliation between intermediaries. A token-based record is append-only and shared, which means reconciliation becomes native rather than scheduled. Auditors, counterparties, and regulators can in principle verify ownership state against the same ledger at the same time. For a broader framing of how this generalizes beyond MMFs, see our primer on how on-chain assets work in finance.
Operational friction and speed
Legacy MMF mobilization is slow because every state change traverses multiple intermediaries. Tokenized rails compress that path. Compliance controls are additive rather than substitutive: traditional investor onboarding persists, and smart-contract whitelists layer on top. The underlying risk profile, exposure to short-duration high-quality government securities, is materially unchanged.
Takeaway: The operational layer shifts; the credit and liquidity risk of the underlying portfolio does not. Diligence should focus on issuer, smart-contract, and chain-level risk, not on reunderwriting the MMF itself.
Regulatory Landscape and Open Questions
Regulation here is bifurcated by fund structure, and the bifurcation matters more than the technology.
Current frameworks and registered vs. private fund structures
Registered tMMFs such as Franklin Templeton's FOBXX operate under the Investment Company Act of 1940, which imposes disclosure, liquidity risk management, portfolio maturity, and liquid-asset-minimum requirements. Private tokenized funds like BUIDL are exempt from many of these provisions, which reduces public visibility into their operations. The New York Fed explicitly notes that regulators and the public have limited insight into whether private tokenized funds implement the same liquidity risk management tools, such as portfolio maturity maximums and liquid asset minimums, that registered MMFs must.
This is not a technology distinction. It is a securities-law distinction that happens to apply to tokenized products. For allocators, the practical implication is that two tMMFs with similar on-chain mechanics can have very different disclosure regimes behind them.
Key risks regulators are watching
Globally, regulators are converging on clearer digital-asset guidelines covering AML, consumer protection, and licensing, but no unified cross-border framework exists yet for tMMFs specifically. Permissioned blockchain architectures have become the dominant compliance choice because transfer restrictions enforced at the smart-contract layer can satisfy investor eligibility requirements without relying only on off-chain gatekeeping. For a European-specific view on how fund regulation is adapting, our analysis of EU MiCA 2.0 and its implications for funds covers the next phase of the framework.
AUM is outrunning the rulebook. Per the New York Fed, BUIDL sits at roughly $2.5B, FOBXX at $708M, and USYC at $488M as of mid-2025. The private-fund wrapper currently dominates total tMMF AUM, which concentrates assets in the structure with the weakest disclosure regime.
Takeaway: The regulatory question is not whether tMMFs are legal. They are. It is whether private-fund structures carrying most of the AUM will face tighter disclosure as the category scales.
What Allocators and Builders Should Take Away
The analytical frame is simple: same asset, different rails. The practical implications split cleanly by audience.
For institutional treasurers
The primary edge is collateral efficiency. Intraday mobility without redemption cycles or T+1 lag changes the practical utility of cash-like holdings in active portfolio management. Treasurers managing margin obligations, cross-venue collateral, or multi-entity cash pooling can realize operational savings that are hard to replicate on legacy rails. The frictions remain real: KYC and whitelisting restrict counterparty breadth, and cross-chain interoperability is still immature. Allocators should underwrite the issuer, the chain, and the smart contract as separate risk vectors, in addition to the usual MMF credit and liquidity diligence.
For protocol and DeFi builders
For DAO treasuries and protocol balance sheets, tMMFs are a yield-bearing alternative to idle stablecoins that preserves capital and earns short-duration Treasury yield. That is a meaningful step beyond USDC sitting in a multisig earning zero. The constraints are the same ones institutions face: whitelisting restricts which protocol wallets can hold the tokens, and composability with existing DeFi primitives is limited precisely because the tokens are permissioned. Builders considering tMMF integration should evaluate issuer-level composability permissions before designing around the token.
Takeaway: tMMFs are infrastructure for a familiar asset. The open question is not whether they grow, but whether the private-fund structures dominating current AUM will face tighter disclosure requirements as regulators catch up to scale.
FAQ: Frequently Asked Questions
What is a tokenized money market fund?
A tokenized money market fund is a traditional MMF whose shares are represented as digital tokens on a blockchain. The underlying portfolio of short-duration government securities and cash is unchanged; only the ownership record and transfer mechanics move on-chain.
How is a tokenized MMF different from a stablecoin?
A stablecoin is a non-regulated or lightly regulated digital asset pegged to a reference value. A tMMF is a regulated fund share with underlying exposure to short-duration government securities, pays yield, and sits inside an issuer structure like the 1940 Act or a private-fund exemption.
What blockchains are tokenized money market funds issued on?
Live tMMFs are issued across both public and permissioned chains. BUIDL launched on Ethereum and has expanded to additional networks; FOBXX uses Stellar and Polygon; USYC operates on Ethereum and other EVM chains. Issuers typically select chains based on institutional custody support and regulatory posture.
Are tokenized money market funds regulated?
Yes, but under different regimes. Registered tMMFs like FOBXX fall under the Investment Company Act of 1940 with full disclosure and liquidity requirements. Private tokenized funds like BUIDL are exempt from many of those requirements, operating under private-placement rules with less public visibility.
Who can invest in tokenized money market funds?
Access is restricted to KYC-approved investors on a whitelist maintained at the smart-contract level. In practice this means institutions, qualified purchasers, and vetted crypto-native entities. Retail access is limited; private-fund tMMFs are generally restricted to accredited or qualified investors under securities law.
What are the risks of tokenized money market funds?
The underlying MMF carries standard credit, interest-rate, and liquidity risk. Tokenization adds smart-contract risk, chain-level operational risk, issuer and transfer-agent risk, and, for private funds, reduced disclosure. Diligence should underwrite each layer separately rather than treating the token as the whole product.
How does settlement work in a tokenized MMF?
Subscriptions and redemptions settle in fiat or stablecoins, with tokens minted or burned at the issuer address. Secondary transfers between whitelisted investors occur as direct ledger updates. Atomic delivery-versus-payment via smart contracts links asset and payment legs, eliminating principal risk in the settlement window.
What are the largest tokenized money market funds by AUM?
According to the New York Fed's September 2025 analysis, BlackRock's BUIDL leads at roughly $2.5B in AUM, followed by Franklin Templeton's FOBXX at $708M and Circle/Hashnote's USYC at $488M. The category has grown faster than most formal regulatory guidance in the United States.
Conclusion
Tokenized money market funds are the clearest example to date of what tokenization is actually good for: it modernizes an operational layer that was already functional but slow, without altering what the investor owns. The analytical mistake to avoid is treating tMMFs as a new asset class or as a crypto product. They are MMF shares with better rails. The second mistake is underpricing the structural split between registered and private tokenized funds, where most of today's AUM sits in the wrapper with the weakest disclosure regime. Whether that gap narrows will shape the next phase of the category more than any technical upgrade.